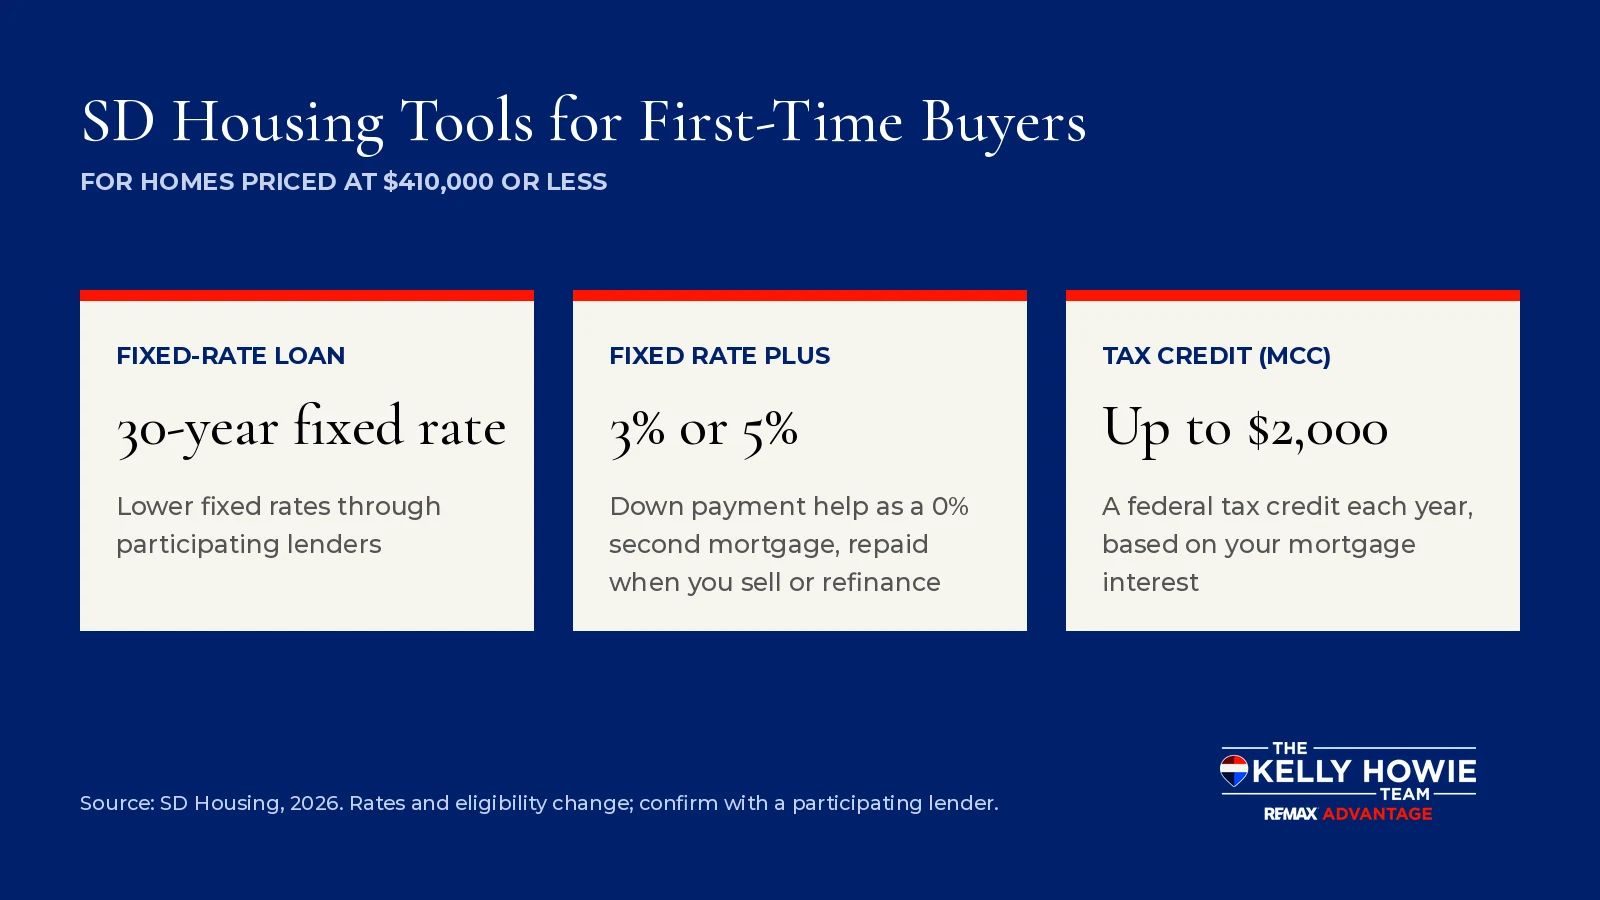
A first-time home buyer in Rapid City, SD is anyone who hasn’t owned a home in the past three years, and South Dakota’s housing agency gives that buyer three main tools: low fixed-rate loans, down payment help of 3% or 5% as a 0% second mortgage, and a federal tax credit of up to $2,000 a year. All three apply to homes priced at $410,000 or less.
With Rapid City’s median home value at $299,400, a large share of Rapid City real estate fits under that cap. The first step is pre-approval with an SD Housing participating lender.
Key takeaways
- Buying a $300,000 home with 5% down costs about $900 to $1,100 more a month than the median rent at today’s rates.
- SD Housing’s first-time fixed rates run about $110 to $180 a month below the national average on that loan.
- Fixed Rate Plus is a 0% loan, not a grant, and you repay it when you sell or refinance.
- SD Housing sets income limits but publishes no minimum credit score; your lender sets that.
How Much Does a First Home Cost in Rapid City?
Two numbers frame a first-time budget here: what homes are worth and what the monthly payment looks like next to rent.
Rapid City Prices vs the $410,000 Cap
The Census Bureau puts the median value of an owner-occupied Rapid City home at $299,400 for 2020 to 2024, which leaves $110,600 of room under the SD Housing cap.
Because that is a five-year figure, it trails the market, so check current homes for sale in Rapid City to see what sits under the cap today.
Monthly Payment vs Rent
Buying costs more each month than renting right now. SD Housing’s rates narrow the gap but don’t close it. Here is a $300,000 home with 5% down next to the median rent:
| Option | Rate | Monthly payment* | More than renting |
| Rent (Census median gross rent) | n/a | $1,109 | n/a |
| Buy at the national average (Freddie Mac, Oct. 22, 2026) | 7.32% | $2,208 | +$1,099 |
| SD Housing Fixed Rate, conventional | 6.750% | $2,099 | +$990 |
| SD Housing Fixed Rate, FHA/VA/USDA | 6.375% | $2,028 | +$919 |
| SD Housing Fixed Rate Plus 5%, conventional | 7.375% | $2,218 | +$1,109 |
*Principal, interest and a 1.00% property tax rate on a $285,000 loan. Excludes mortgage insurance, homeowners insurance and HOA dues. SD Housing rates are from September 29, 2026 and change often.
The program’s fixed rates save about $110 to $180 a month against the national average. Fixed Rate Plus costs about the same each month as a market-rate loan, but it covers $14,250 of up-front costs on this purchase.
South Dakota First-Time Homebuyer Programs
SD Housing, the state housing finance agency, runs four tools a first-time buyer in Rapid City can compare or combine. Each one works through a participating lender, not through the agency directly.
SD Housing First-Time Homebuyer Program
SD Housing offers 30-year fixed-rate loans through participating lenders. You qualify if you haven’t owned a home in the past three years, your income is at or below its limits, and the price is $410,000 or less.
Living in a mobile home that wasn’t on a permanent foundation doesn’t count as prior ownership, and veterans can ask a lender whether an exception applies. The eligibility rules list every condition. As of September 29, 2026, first-time fixed rates were 6.375% for FHA, VA and USDA loans and 6.750% for conventional.
Fixed Rate Plus Down Payment Assistance
Down payment assistance in South Dakota runs through Fixed Rate Plus. It adds 3% or 5% of your first mortgage as a second mortgage at 0% interest, with no monthly payments and no added fees, repaid when you sell or pay off the loan.
Anyone searching for first-time homebuyer grants in South Dakota should know this is the closest SD Housing offers, and it is a loan, not a grant. The trade-off is a higher first-mortgage rate: 7.125% or 7.375% on a conventional loan.
Mortgage Credit Certificate (Tax Credit)
The Mortgage Credit Certificate turns part of your yearly mortgage interest into a federal tax credit. SD Housing’s tax credit brochure caps it at $2,000 a year, with a $250 fee when paired with the first-time program; lenders may add up to $250. MCC loans use the repeat-buyer rate column, 7.750% for conventional.
On the $285,000 loan above, that’s about $193 more a month against a credit worth up to $167 a month, so ask your lender to run it both ways. Selling within nine years can trigger a federal recapture tax, and SD Housing reimburses what you actually pay.
FHA, VA and USDA Loans
SD Housing offers all three as government loan types. FHA allows a lower down payment and more flexible credit. VA gives eligible veterans, service members and surviving spouses no down payment and no monthly mortgage insurance.
USDA serves eligible rural areas. Ellsworth AFB households can compare their options with VA loan homes in Rapid City.
Income Limits and Credit Requirements in South Dakota
Two things decide whether the first-time program fits: your household income and the credit profile your lender will accept.
Income Limits
SD Housing sets a maximum income by county and household size in its income limits PDF. It counts annualized gross income from all sources, so overtime, bonuses and commission count too.
Credit Score and Down Payment
SD Housing doesn’t publish a minimum credit score for the first-time program. Your lender reviews credit, income and debt, and each loan type sets its own floor. The down payment depends on the loan:
- FHA: starts at 3.5% down.
- Conventional: as little as 3% down on many programs.
- VA and USDA: no down payment for eligible buyers.
How to Buy Your First Home in Rapid City, Step by Step
Buying a house in Rapid City follows the same path for most first-timers, and it mirrors the statewide process for buying a house in South Dakota.
Seven Steps From Budget to Keys
- Check your finances. Look at your credit, debt-to-income ratio and savings.
- Take homebuyer education. SD Housing partners offer a free course online, one-on-one or in a group.
- Get pre-approved. Pick an SD Housing participating lender.
- Choose an area. Compare price and commute across Rapid City neighborhoods.
- Hire a buyer’s agent. The Kelly Howie Team offers no-pressure buyer consultations.
- Make an offer and inspect. Inspection periods of about 10 days are typical here.
- Close and get your keys.
What Surprises First-Time Buyers on Tours
Many first-time buyers don’t expect how common finished basements and below-grade living space are in Rapid City, and that space is often a way to get more square footage within a budget.
Price can surprise buyers too. Two homes with similar square footage can sell for very different amounts depending on the neighborhood, condition and location within the Black Hills. More of these Black Hills home buying surprises show up once you start touring.
How Much Should You Save After Buying a House?
The down payment isn’t the last check you write. Plan for upkeep from the first year.
Keep a Repair Fund
Fannie Mae suggests setting aside 1% to 4% of your home’s value each year for maintenance, and more for homes over 30 years old. Keep it separate from your emergency savings.
- $300,000 home: $3,000 to $12,000 a year.
- $410,000 home (the SD Housing cap): $4,100 to $16,400 a year.
Talk to a Rapid City Buyer’s Agent
A lender tells you what you qualify for. An agent tells you what that buys.
Turn a Pre-Approval Into a Shortlist
The Kelly Howie Team can show you how a first-time budget plays out across Rapid City real estate, from townhomes to single-family homes. When you’re ready to compare your rent with a real payment, reach out to the team.
First-Time Homebuyer FAQs
SD Housing doesn’t offer a true grant. Its closest option is Fixed Rate Plus, a 0% second mortgage worth 3% or 5% of your loan with no monthly payments, repaid when you sell or refinance. The Mortgage Credit Certificate adds a federal tax credit of up to $2,000 a year.
SD Housing sets a maximum income, not a minimum. Your lender decides what you can afford by reviewing your income, credit and debt. For the limit, SD Housing counts annualized gross income from all sources, and the cap depends on your county and household size.
It depends on the program, county and household size. HUD defines low income as 80% of area median income and publishes limits by metro area and county. SD Housing’s first-time program uses its own limits, so check your household against them and ask your lender which applies.
Start with SD Housing’s eligibility rules and its free homebuyer education course. Then get pre-approved by a participating lender so you know your budget. After that, talk with a local buyer’s agent about which Rapid City neighborhoods fit your payment and what your budget buys right now.